
Buying a car when you have bad credit can feel like an impossible mission. You walk into dealerships, sit in the office, and within minutes, the dealer says, “Sorry, we can’t work with your credit score right now.” It’s frustrating, disheartening, and leaves you wondering if you’ll ever drive off the lot without a mountain of cash or a co-signer. But here is the good news: zero down bad credit car dealers near me is not just a search term; it’s a lifeline for thousands of people every day. There are specific types of dealerships designed exactly for this scenario. They exist to help subprime borrowers get approved, even with bankruptcies, repossessions, or collections on their record.
This guide will break down exactly how these dealers work, where to find them, what to expect, and most importantly, how to secure the best deal possible despite your credit history. We will dive deep into the mechanics of “buy here pay here” (BHPH) lots, traditional dealers who specialize in subprime lending, and the hidden fees that might catch you off guard. By the end of this article, you will know exactly how to navigate the landscape of zero-down, bad-credit auto financing.
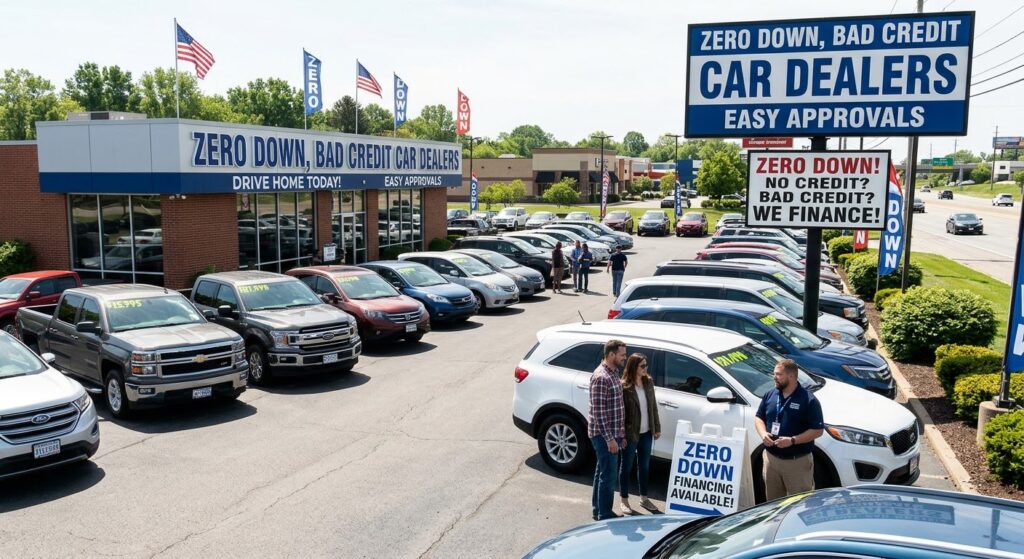
Understanding the Landscape: Who Are These Dealers?
When you search for “zero down bad credit car dealers near me,” you are primarily looking at two distinct categories of businesses. Understanding the difference between them is crucial because they operate very differently under the hood.
1. Buy Here Pay Here (BHPH) Dealerships
The most common answer to your search query is the BHP dealership. Also known as “repos lots,” these dealers sell cars directly to customers and act as the bank. Instead of sending your application to a third-party lender like Chase, Wells Fargo, or a local credit union, you make your payments directly to the dealership.
Why do they offer zero down? Because they already own the inventory. They don’t need to worry about a wholesaler selling the car away from you. They have used cars on their lot, often high-mileage models that other banks wouldn’t touch. Since they control the entire process—from sales to financing to collection—they can afford to take risks on risky borrowers.
However, there is a trade-off. BHPH dealers often charge higher interest rates than traditional lenders. You might see APRs ranging from 15% to 25%, sometimes even higher. Additionally, they may require weekly payments rather than monthly, which can be a hurdle if you are paid bi-weekly or monthly. Some dealers also install GPS trackers or kill switches in the vehicles, meaning if you miss a payment, they can remotely disable the car. While this sounds harsh, it is standard practice for BHPH lots because they are insuring you against default.
2. Traditional Dealers with Subprime Financing Programs
Not all bad credit dealers are BHPH lots. Many traditional franchise dealerships (like Ford, Toyota, or Honda dealers) have dedicated “subprime departments.” These dealers work with a network of “second-chance” lenders who specialize in bad credit.
These dealers might ask for a small down payment (like $500 or $1,000), but some advertise “zero down” to attract traffic. The key difference here is that you are still dealing with a third-party lender. This can sometimes result in better long-term terms than BHPH, provided you qualify. These dealers often have newer inventory, better warranties, and more transparent pricing structures, though the interest rates will still be elevated compared to prime borrowers.
How to Find “Zero Down Bad Credit Car Dealers Near Me”
Finding the right dealer requires more than just typing keywords into Google. You need to vet the dealers carefully to avoid predatory practices. Here is a step-by-step strategy to locate and verify these dealers in your area.
Use Specialized Directories
Websites like Edmunds, Cars.com, and TrueCar allow you to filter dealers by “Bad Credit Loans” or “Subprime Financing.” Look for dealers who explicitly state they accept poor credit. Additionally, specialized directories like “Buy Here Pay Here” listings aggregate BHPH dealers in specific zip codes. These directories often include customer reviews, which are gold mines for understanding a dealer’s reputation.
Check Google Maps and Reviews
When searching for “bad credit car dealers near me,” look at the Google Maps results. Read the negative reviews specifically. If multiple people complain about “hidden fees,” “high mileage sold as low mileage,” or “harsh repo men,” take note. A dealer with a 3.8-star rating that has detailed, honest complaints is often better than one with a perfect 5.0 rating that looks fake. Look for comments mentioning “easy approval” or “worked with my bankruptcy.”
Visit Local Lots in Person
Drive through industrial areas or commercial strips in your city. BHPH dealers often cluster together in specific zones. Seeing the cars physically helps. Look for lots that are well-maintained. A messy lot doesn’t mean bad quality, but it can indicate disorganization. More importantly, talk to the salespeople. Ask them directly: “Do I need a down payment?” “What happens if I miss a payment?” Their answers will tell you a lot about their transparency.
The Fine Print: What to Watch Out For
“Zero down” is a powerful marketing hook, but it is rarely the whole story. To protect yourself, you need to understand the fine print associated with these deals.
Higher Interest Rates
As mentioned, BHPH dealers charge more. If you are offered a $15,000 car with zero down, check the total amount financed. If the monthly payment seems too good to be true, the interest rate is likely inflated. Calculate the total cost of the loan over its life. You might end up paying $22,000 for a $15,000 car. That is the price of accessibility.
Mandatory Add-Ons
Many bad credit dealers tack on mandatory add-ons like extended warranties, gap insurance, or tire and wheel coverage. These can range from $1,000 to $3,000 and are often rolled into your loan. Ask for an itemized list of these products. Do you actually need them? Gap insurance is useful if you finance more than the car is worth, but extended warranties from BHPH dealers are often overpriced and cover little. Negotiate these out if possible.
The “Payment Pack”
Some dealers focus solely on the monthly payment, not the price of the car. They might sell you a $10,000 car and make it look like a $15,000 car by extending the loan term to six or seven years. This lowers your monthly payment but increases the total interest you pay significantly. Always look at the total price of the vehicle, not just the monthly bill.
Prepayment Penalties
Check if your loan has a prepayment penalty. Some BHPH dealers charge a fee if you pay off the loan early. This discourages you from refinancing later when your credit improves. Ideally, you want a loan that allows you to pay extra toward the principal without penalty. This helps you build equity faster and reduces the total interest paid.
Tips for Getting Approved
Even with zero-down programs, approval isn’t guaranteed. Here are actionable tips to increase your chances of getting approved by bad credit dealers near you.
Prove Your Stability
Dealers care less about your credit score and more about your ability to pay now. Bring proof of income: recent pay stubs, bank statements, or tax returns. If you are self-employed, bring your profit and loss statement. Showing steady employment reassures the dealer that you have a reliable source of funds.
Reduce Your Debt-to-Income Ratio
Before applying, try to pay down any existing debts. If you have credit card balances, pay them off. This lowers your debt-to-income ratio, making you look more responsible to the dealer. Even if you aren’t using traditional credit, showing that you manage other obligations well helps.
Bring a Co-Signer if Possible
While BHPH dealers often don’t require co-signers, having one can help. A co-signer with decent credit can lower your interest rate or help you qualify for a better vehicle. However, ensure the co-signer understands the risk: if you default, they are liable for the debt.
Be Honest About Your History
If you have a past bankruptcy or repossession, disclose it upfront. Hiding it can lead to rejection later. Dealers appreciate honesty because it shows you are trustworthy. Explain why the financial hiccup happened and how your situation has improved.
Shop Around
Don’t settle for the first dealer who says yes. Visit three to five different BHPH lots. Compare their prices, interest rates, and terms. Use competing offers as leverage. If Dealer A offers you a car for $200 a month, show that quote to Dealer B and ask if they can beat it. Competition works in your favor.
The Process: From Search to Drive-Off
Once you find a dealer, the process usually follows a predictable pattern. Knowing what to expect reduces anxiety.
- Application: Fill out a simple application. Provide personal info, employment details, and references.
- Verification: The dealer verifies your identity, income, and residence. This takes 15–30 minutes.
- Selection: Choose a car from the lot. Test drive it if allowed. Some BHPH lots limit test drives due to insurance costs.
- Financing Approval: The dealer runs a soft credit check or checks your banking history. Approval is often instant.
- Paperwork: Sign the contract. Read every line. Ensure the zero-down term is clearly stated.
- Delivery: Take possession of the car. Get your keys, registration, and insurance proof.
Why Zero Down Matters for Bad Credit Buyers
A down payment serves two purposes: it reduces the loan amount and shows the lender you have “skin in the game.” For bad credit buyers, saving for a large down payment can take months or years. Zero down removes this barrier, allowing you to get back on the road immediately. This is crucial for maintaining employment. If your car breaks down and you lose your job, your credit worsens further. Zero down keeps you mobile and earning, which is the best way to rebuild your credit.
Furthermore, zero-down loans can help you establish a new payment history. If you make consistent payments on a BHPH loan, some dealers report to credit bureaus. This can slowly improve your credit score, opening doors to better financing options in the future.
Alternatives to Consider
If zero-down bad credit dealers seem too expensive or risky, consider these alternatives:
- Credit Union Auto Loans: Many credit unions offer “secured auto loans” where the car itself is collateral. They often have lower rates than BHPH dealers.
- Family Loans: Borrowing from family or friends might come with zero interest, saving you thousands.
- Used Car Marketplaces: Platforms like Carvana or Vroom sometimes offer flexible financing options, though they may require a small down payment.
Conclusion
Searching for “zero down bad credit car dealers near me” opens the door to a world of opportunities for those with imperfect credit. While BHPH dealers and subprime lenders charge a premium for this convenience, they provide a vital service: access to transportation when traditional banks say no. By understanding the landscape, reading the fine print, and negotiating wisely, you can secure a fair deal. Remember, the goal isn’t just to get a car; it’s to get a car that helps you rebuild your financial life. Be diligent, be patient, and drive with confidence.
Disclaimer: The information provided in this article is for educational purposes only and does not constitute financial, legal, or investment advice. Auto financing terms, interest rates, and dealer policies vary by location and individual circumstances. Always read your contract carefully before signing. “Zero down” may still require taxes, title, and registration fees to be paid at closing. Consult with a qualified financial advisor or attorney for advice tailored to your specific situation.