
In the bustling world of personal finance, few decisions carry as much weight or long-term impact as purchasing a vehicle. Whether you are buying your first car, upgrading a family sedan, or investing in a commercial fleet, the financial mechanics behind the transaction can often feel overwhelming. This is where a reliable car mortgage calculator becomes an indispensable tool. Often referred to interchangeably with auto loan calculators, these digital aids strip away the ambiguity of monthly payments and reveal the true cost of borrowing. By understanding how these calculators work, you can negotiate better rates, avoid predatory lending traps, and ensure that your new ride fits comfortably within your budget without causing financial strain down the road.
Understanding the Core Components
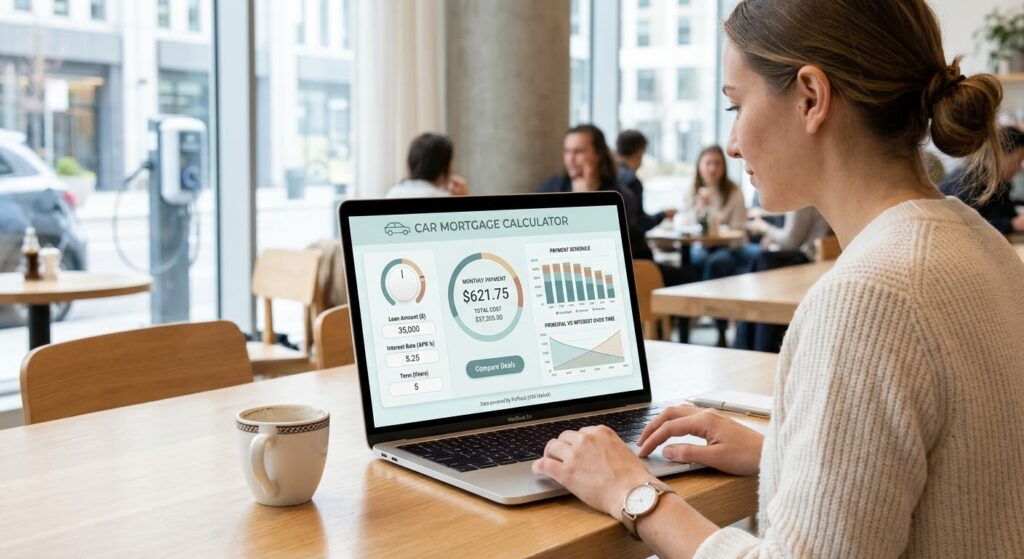
To truly utilize a car mortgage calculator, one must first understand the variables that drive the numbers. Every calculation rests on four primary pillars: the principal amount, the interest rate, the loan term, and sometimes the down payment or trade-in value. The principal is the total amount of money you borrow to purchase the vehicle. It is crucial to note that this figure often differs from the sticker price of the car because it may include taxes, registration fees, and dealer add-ons if those costs are rolled into the loan.
The interest rate, expressed as an annual percentage rate (APR), represents the cost of borrowing money over time. This rate is not arbitrary; it is determined by your credit score, income stability, debt-to-income ratio, and current economic conditions. A lower interest rate means less money paid to the lender over the life of the loan, while a higher rate can significantly inflate the total cost. The loan term refers to the duration over which you will repay the loan. Common terms range from thirty-six months to seventy-two months, though some lenders offer terms extending up to eighty-four months or more. Finally, the down payment is the upfront cash you pay toward the purchase. A larger down payment reduces the principal, thereby lowering both the monthly payment and the total interest paid.
How the Calculation Works
The mathematics behind a car mortgage calculator rely on the concept of amortization. Amortization is the process of paying off a debt over time through regular payments. Each payment covers two components: interest and principal. In the early stages of the loan, a larger portion of each payment goes toward interest, while a smaller portion reduces the principal balance. As the loan progresses, this dynamic shifts, and more of each payment is applied to the principal. Most standard car loans use a fixed-rate amortizing structure, meaning the monthly payment remains constant throughout the loan term, even though the proportion of interest to principal changes.
When you input your details into a calculator, it uses a specific formula to determine your monthly payment. The formula takes into account the principal loan amount, the monthly interest rate (which is the annual rate divided by twelve), and the total number of payments (the loan term in years multiplied by twelve). The result is a precise monthly figure. Beyond the monthly payment, the calculator also provides the total interest paid over the life of the loan and the total cost of the vehicle including interest. This holistic view allows borrowers to see the full picture rather than just focusing on whether the monthly bill feels affordable.
Why Use a Car Mortgage Calculator?
The primary benefit of using a car mortgage calculator is clarity. Lenders often present deals in ways that obscure the true cost. They might highlight low monthly payments without mentioning that they come with a longer loan term and a higher interest rate. By running the numbers yourself, you can compare different scenarios side by side. For instance, you might discover that choosing a shorter loan term with a slightly higher monthly payment actually saves you thousands of dollars in interest over time.
Another significant advantage is negotiation power. When you know exactly what your monthly payment should be for a given interest rate and loan amount, you can identify when a dealer is inflating costs through hidden fees or unfavorable terms. You can also experiment with different down payment amounts to see how much they impact your monthly obligations. If you have limited cash on hand but want to minimize interest, the calculator can show you the optimal balance between a larger down payment and a shorter loan term.
Furthermore, these tools help prevent buyer’s remorse. Many people stretch their budgets to the limit, approving a loan they can barely afford. By calculating payments beforehand, you can set a realistic budget that accounts for other expenses like insurance, fuel, maintenance, and parking. This ensures that your new car enhances your life rather than becoming a financial burden that limits your ability to save or invest elsewhere.
Factors That Influence Your Rate
While the calculator provides the mathematical framework, several external factors influence the variables you input. Your credit score is perhaps the most critical determinant of your interest rate. Borrowers with excellent credit scores typically qualify for the lowest rates, while those with fair or poor credit may face significantly higher rates. This disparity can mean tens of thousands of dollars difference in total cost over the life of the loan. Therefore, checking your credit report before shopping for a car is essential. Disputing errors and paying down existing debts can improve your score and unlock better loan terms.
The type of vehicle also plays a role. New cars often come with lower interest rates because they are less risky collateral and frequently subsidized by manufacturers to encourage sales. Used cars may have higher rates due to the increased risk of mechanical issues and faster depreciation. Additionally, the length of the loan term affects the interest rate. Longer terms often come with slightly higher rates because the lender assumes more risk over a longer period. However, the difference is usually marginal compared to the impact of creditworthiness.
Economic conditions such as inflation and central bank policies also influence rates. When the Federal Reserve raises interest rates to combat inflation, auto loan rates tend to rise as well. Conversely, during periods of economic downturn, rates may drop. While you cannot control macroeconomic trends, being aware of them helps you time your purchase strategically. If rates are projected to rise, locking in a loan sooner rather than later might be prudent.
Maximizing Your Savings
To get the most out of your car mortgage calculator experience, consider experimenting with multiple scenarios. Start by adjusting the loan term. Compare a thirty-six-month loan against a sixty-month loan. You will likely find that the shorter term has a higher monthly payment but results in substantial savings on interest. If the higher monthly payment is feasible, opting for a shorter term is almost always financially superior.
Next, play with the down payment amount. A common rule of thumb is to put down at least twenty percent of the vehicle’s value. However, depending on your cash flow, you might choose a lower down payment to keep more liquidity in your pocket. The calculator will show you the trade-off: a smaller down payment means higher monthly payments and more total interest, but it preserves your emergency fund. Find the balance that works best for your financial situation.
Don’t forget about the trade-in value. If you are trading in an old vehicle, its value can be applied as a down payment, reducing the principal. Be sure to research the market value of your trade-in independently so you don’t accept a lowball offer from the dealer. Inputting this value into the calculator gives you a clearer picture of your net loan amount.
Finally, consider pre-approval from banks or credit unions before visiting the dealership. Pre-approval gives you a baseline interest rate and loan amount, empowering you to negotiate from a position of strength. You can then approach the dealer with your own financing or ask them to beat the pre-approved rate. Using the calculator, you can quickly assess whether the dealer’s offer is competitive.
Common Mistakes to Avoid
One frequent mistake is focusing solely on the monthly payment without considering the total cost. A dealer might offer a “low monthly payment” by extending the loan term to eight years. While the monthly bill looks attractive, you could end up paying double the car’s value in interest. Always look at the total interest and total cost figures provided by the calculator.
Another error is rolling negative equity from a previous loan into the new loan. If you owe more on your trade-in than it is worth, that difference is added to your new loan amount. This increases the principal, leading to higher payments and more interest. Be cautious of “negative equity rollover,” especially if the vehicle depreciates rapidly.
Ignoring additional costs is also common. Some calculators only factor in the loan principal and interest. However, you must also account for sales tax, documentation fees, title fees, and insurance premiums. These costs can add thousands to your overall expense. Ensure your budget includes these recurring and one-time costs to avoid surprises.
Lastly, failing to shop around for the best rate is a costly oversight. Different lenders offer vastly different terms. Credit unions often provide lower rates than traditional banks, and online lenders may have competitive offers due to lower overhead. Use the calculator to compare quotes from multiple sources. Even a half-percent difference in interest rate can save you hundreds of dollars over the life of the loan.
The Role of Technology in Modern Car Buying
Technology has transformed how we calculate and manage auto loans. Modern car mortgage calculators are available on websites, mobile apps, and even within dealership portals. They are user-friendly, intuitive, and often allow real-time adjustments. Some advanced calculators even incorporate historical data to predict future rate trends or suggest optimal loan structures based on your spending habits.
Digital platforms also enable seamless integration with lender databases. When you enter your information, the calculator can instantly pull pre-qualified offers from multiple lenders. This reduces the friction of applying for loans and speeds up the approval process. Some tools even allow you to lock in a rate temporarily while you shop for the perfect car.
Moreover, technology facilitates transparency. With a few clicks, you can access detailed amortization schedules that break down every payment into principal and interest. This level of detail helps borrowers understand exactly how their money is being allocated. It also empowers them to make extra payments toward the principal if they wish, accelerating the payoff process and reducing total interest.
As electric vehicles and subscription-based car models gain popularity, calculators are evolving to accommodate these new formats. Subscription services often have different cost structures, requiring different calculation methods. Future iterations of these tools will likely adapt to reflect the changing landscape of automotive finance, ensuring that consumers remain informed regardless of how they acquire their vehicle.
Conclusion
A car mortgage calculator is more than just a math tool; it is a strategic asset in your journey to vehicle ownership. By mastering its use, you gain insight into the true cost of borrowing, uncover opportunities for savings, and negotiate with confidence. Remember to consider all variables—principal, interest rate, term, and additional fees—to make an informed decision. Whether you are a first-time buyer or a seasoned driver, leveraging these calculators ensures that your car purchase aligns with your financial goals. In a world where financial products can be complex and opaque, clarity is power. Let the numbers guide you, and drive away with peace of mind knowing you secured the best possible deal.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice. Interest rates, loan terms, and fees can vary significantly depending on your location, credit history, and the specific lender. Always consult with a qualified financial advisor or loan officer before making significant financial decisions. The calculations mentioned are estimates based on standard amortization formulas and may not reflect exact figures offered by any specific financial institution.